How to plan a home purchase without derailing your other goals
Deposit, borrowing capacity, inflation and timing: how to plan a home purchase while still funding studies, retirement and family projects.
Introduction: The Great Homeownership Trap
For most married couples, buying a first home feels like the ultimate rite of passage. It’s the physical embodiment of "making it"—the place where you will plant a garden, host holiday dinners, and watch your life unfold together. Zillow tabs become your late-night entertainment, and neighborhood open houses turn into weekend dates.
Yet, there is a dark side to the American Dream of homeownership that nobody talks about until it's too late: House Poor Syndrome. This occurs when a couple pours every available dollar, every bonus, and every ounce of emotional energy into securing a mortgage down payment, only to realize that they have completely hollowed out their financial life in the process.
Suddenly, you own a beautiful four-bedroom house, but you can’t afford to go out to dinner, you’ve stopped contributing to your retirement accounts, your emergency fund is wiped out, and every minor plumbing leak induces a panic attack.When financial stress creeps back into your marriage over a squeaky floorboard or an unexpected property tax hike, the home that was supposed to bring you joy becomes a gilded cage.
Buying a home shouldn't require financial self-destruction. In this comprehensive guide, we will explore how married couples can plan, save, and buy a home while actively protecting their retirement, maintaining their sanity, and nurturing their relationship.
1. The Emotional Pitfall: Aligning Dreams vs. External Pressure
Before looking at a single mortgage rate or calculating a down payment, you and your spouse need to have an honest conversation about why you want to buy a house right now.
Too often, couples buy homes because of external timelines rather than internal readiness. Parents ask, "When are you finally going to buy?" Friends on social media are posting keys-in-hand photos. Rent increases feel frustrating, making buying look like the immediate escape hatch.
However, rushing into real estate because of societal pressure is the fastest way to derail your broader life projects. Ask yourselves these crucial questions:
Are we buying this home because we plan to live in this city for the next 7 to 10 years, or because we feel like adults are "supposed" to own property by a certain age?
Is our desire for a home aligned with our other major goals, like starting a family, traveling, or launching a business?
What are we willing to pause or scale back, and what is non-negotiable? (e.g., "We are willing to cut restaurant dining in half, but we will not stop contributing to our retirement match.")
2. Phase 1: Crafting Your Comprehensive Financial Roadmap
A home purchase is rarely just a housing decision; it is a massive capital allocation event. To prevent it from swallowing your financial life, it must be integrated into a broader Financial Roadmap.
Many couples make the mistake of saving in a vacuum. They throw money into a "House Fund" while ignoring everything else. When the house is finally bought, they have to start from zero on retirement, car replacements, and vacations.
The Holistic Wealth Formula
A healthy roadmap balances three pillars simultaneously:
The Safety Pillar: An emergency fund that covers 3 to 6 months of living expenses (calculated based on your future mortgage payment, not your current rent).
The Future Pillar: Consistent retirement contributions (at least capturing employer matches) so compounding interest never stops working for you.
The Project Pillar: The dedicated real estate fund (down payment, closing costs, moving expenses, and a post-purchase buffer).
Let’s look at real numbers to see how this works in practice for a typical married couple.
3. Phase 2: The Numbers Game (Real Dollar Breakdown)
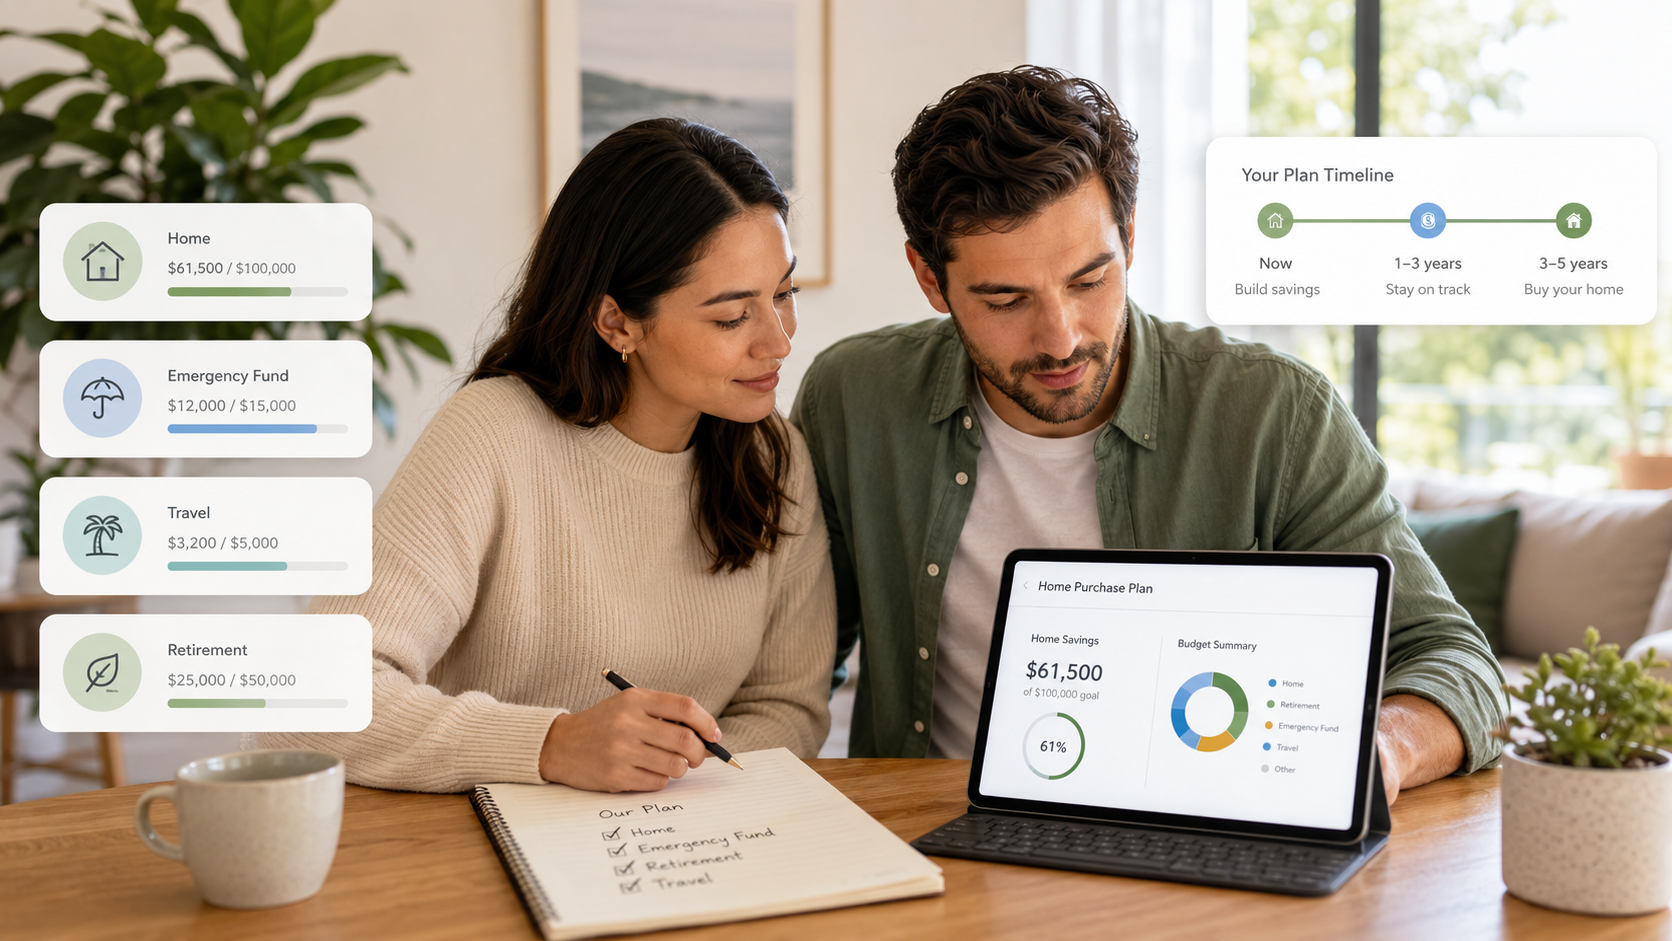
Let’s introduce Marcus and Rachel, a married couple in their early 30s with a combined net monthly income of $8,000($96,000 per year after taxes). They currently rent an apartment for $1,600/month and want to buy a home priced at $400,000 within three years.
To buy this home safely, Marcus and Rachel map out their exact target:
10% Down Payment: $40,000 (Opting for 10% instead of 20% allows them to buy sooner without draining every account, while factoring in Private Mortgage Insurance (PMI) as a short-term cost).
Closing Costs & Escrows (approx. 3%): $12,000.
Post-Move Emergency Buffer: $8,000 (Crucial for immediate repairs, appliances, or painting).
Total Real Estate Target: $60,000.
| Category | Monthly Amount | Where It Goes |
|---|---|---|
| Needs (Survival) | $3,800 | Current Rent ($1,600), Groceries ($700), Utilities/Internet ($350), Car Payments/Gas ($650), Health Insurance ($500). |
| Wants (Lifestyle) | $2,000 | Dining/Coffee ($350), Entertainment/Dates ($250), Personal Allowances (Marcus: $300, Rachel: $300), Annual Vacation Fund ($500), Subscriptions ($300). |
| Retirement & Wealth | $1,000 | 401(k) / IRA Contributions ($1,000 to maintain compounding interest). |
| Home Purchase Fund | $1,200 | Dedicated High-Yield Savings Account (HYSA) for down payment & closing. |
Notice what Marcus and Rachel did here: They did not stop saving for retirement ($1,000/month), and they kept a modest vacation fund ($500/month). They are pacing themselves so that buying a house doesn't require pressing pause on the rest of their lives.
4. Phase 3: Milestone Planning for the 3-Year Home Purchase
Saving $60,000 over 3 years (36 months) requires disciplined pacing. If Marcus and Rachel just tried to save blindly, they would burn out. Instead, they break the journey down into distinct, manageable milestones.
Milestone 1: The Starter Buffer & Debt Clearance (Months 1–12)
Target: Clear $5,000 in legacy student loan/credit card debt and build a $10,000 baseline in the home fund.
Monthly Contribution: $800/month saved + $400 redirected from old debt payments.
Result at Month 12: $10,000 saved, zero toxic debt, and enhanced monthly cash flow.
Milestone 2: The Acceleration Phase (Months 13–24)
Target: Grow the home fund to $32,000.
Monthly Contribution: Increase savings to $1,500/month by securing a minor salary increase and trimming discretionary streaming services.
Result at Month 24: Cumulative savings reach $32,000 (plus interest earned in a 4.5% HYSA).
Milestone 3: The Final Sprint & Tax Bonus (Months 25–36)
Target: Reach the final $60,000 threshold.
Monthly Contribution: Maintain $1,500/month ($18,000/year). Inject 100% of annual tax refunds and work performance bonuses ($5,000 total across the year) directly into the fund.
Result at Month 36: $61,500 safely accumulated. Goal achieved ahead of schedule, leaving a comfortable cash cushion.
By dividing the goal into three clear milestones, Marcus and Rachel turn an intimidating mountain into three manageable foothills. Each milestone reached is celebrated as a couple, keeping morale high.
5. Phase 4: Money & Relationships — Protecting Your Marriage During the Process
House hunting is notoriously stressful. Bidding wars, inspection surprises, mortgage underwriting red tape, and moving logistics can strain even the strongest marriages. When financial pressure is added, arguments can escalate quickly.
Here are three golden rules to protect your relationship while buying a home:
1. Separate "Needs" from "Ego"
When shopping for a home, it’s easy to let ego dictate your choices. You might start looking at granite countertops and three-car garages because "that’s what successful people buy," even if a simpler home suits your actual lifestyle better.
Sit down before you start touring homes and write down your Non-Negotiables (e.g., safe neighborhood, within 30 minutes of work, structurally sound) versus your Nice-to-Haves (e.g., hardwood floors, walk-in closet, updated kitchen).If a house meets all your needs but lacks a cosmetic feature, remember that paint and flooring can be upgraded over time on your regular budget.
2. The Bi-Weekly Real Estate Check-In
Don't let home buying consume every dinner table conversation. When you're in the middle of a purchase, designate specific times to talk logistics. Use a quick 15-minute check-in every two weeks to review mortgage documents,inspection reports, or savings transfers. Outside of that window, make a rule: no real estate talk during date night.
3. Guarding the Post-Purchase Life
The biggest mistake couples make is spending every last dollar at the closing table. When you hand over your cashier's check for the down payment and closing costs, your bank account shouldn't look like a wasteland.
Always ensure you retain your Post-Purchase Emergency Buffer. If your savings target was $60,000, and closing costs end up being slightly higher, do not dip into your retirement accounts to cover the gap. Adjust your expectations on the purchase price instead.
Conclusion: Building a Home Without Breaking Your Future
Buying a home is one of the most exciting chapters of married life, but it shouldn't require you to sacrifice your financial security, your retirement, or your peace of mind.
By stepping back, looking at your broader financial roadmap, breaking your savings target into milestone checkpoints,and keeping communication open with your spouse, you can purchase a home that enhances your life rather than overwhelming it.
Take out a notebook tonight, pour two cups of coffee, and map out your path. Your dream home is waiting—and so is a secure, thriving future.
Turn this into your own plan
Set up your household in ten minutes and see your projects on a real timeline.
Start freeKeep reading
Joint vs. Separate Bank Accounts for Married Couples: Which Is Best?
Budget & SavingWedding Budget Calculator: How Much Will Your Wedding Cost?
Money & RelationshipsHow Much Can You Spend Without Asking Your Partner?
Budget & SavingHow Much Emergency Fund Should We Have Before Starting a Major Project?
Financial RoadmapsWhat Happens Financially If Our Situation Changes? A Practical Guide for Couples
Financial RoadmapsJoint, Separate, or Hybrid Bank Accounts: What Works Best for Couples?
MilestonesMilestone-Based Financial Planning for Couples: A Guide to Securing Your Future Together
Budget & SavingHow to Build a Couple Budget That Actually Works (Without the Fight)
Money & RelationshipsHow to Align Your Financial Goals Before Buying a Home Together
Financial PlanningWhy Most Couples Don't Need a Better Budget — They Need a Better Timeline
Money & RelationshipsFinancial planning vs budgeting: why families need both
BudgetingBudget planning for couples: a simple method that actually lasts
BudgetingBudget planning for couples: a simple method that actually lasts