Financial planning vs budgeting: why families need both
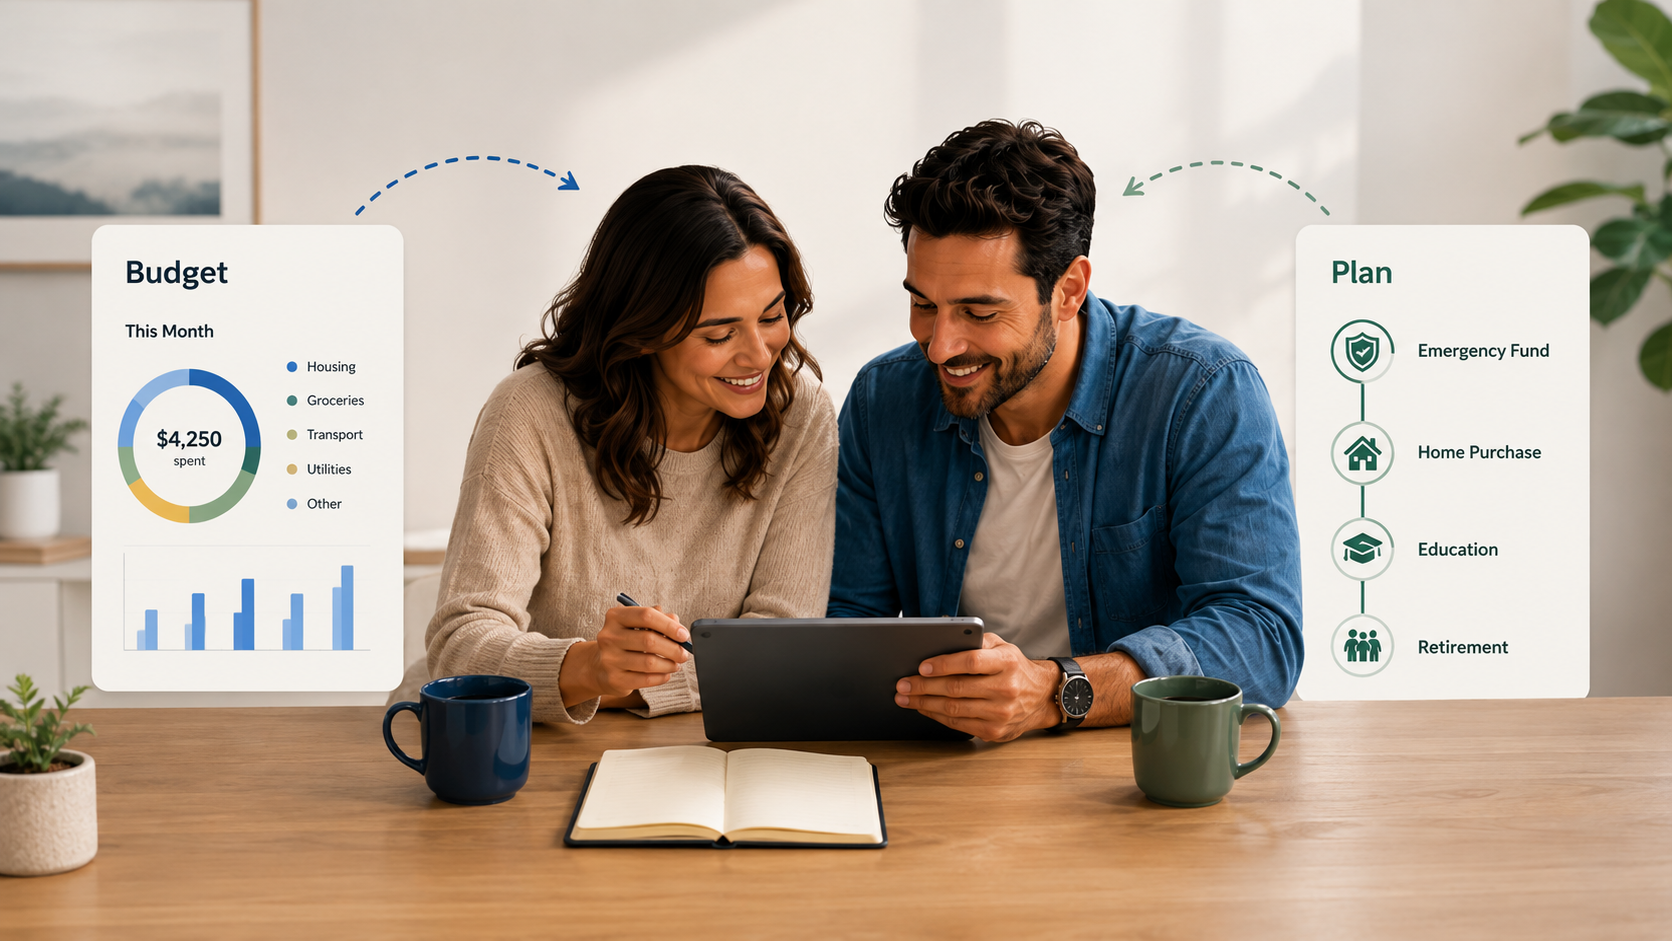
Budgeting controls this month. Financial planning decides the next twenty years. Here is how the two fit together for a household.
Introduction: The Daily Grind vs. The Grand Vision
Picture this scenario: It is Sunday evening. You and your spouse sit down at the kitchen table surrounded by a scattered collection of credit card statements, grocery receipts, and utility bills. One of you looks up, visibly stressed, and says, "Where did all our money go this month? We need to track every single penny more carefully!"
So, you download a budgeting app or spin up a complicated spreadsheet. You categorize every expense down to the last dollar. You feel virtuous and in control for about fourteen days. Then life happens—a car repair, an impromptu birthday dinner, a pediatrician visit—and the meticulous budget shatters. Frustrated, you abandon the system entirely, feeling like you are financially undisciplined.
Here is the hidden truth that most personal finance gurus fail to tell you: Your budget didn't fail because you lack discipline. It failed because a budget is not a plan.
Many married couples treat budgeting and financial planning as interchangeable terms, but they are entirely different tools. Budgeting is about managing the present (where your money goes this week), while financial planning is about designing the future (where your life is heading over the next decade). Confusing the two is why so many families feel like they are working harder than ever while running on a treadmill.
In this article, we will break down the crucial differences between budgeting and financial planning, show you how they work together, and provide concrete dollar examples and milestone roadmaps designed specifically for married couples.
1. The Core Difference: Managing Today vs. Designing Tomorrow
To understand why you need both, let’s look at their distinct roles in your household ecosystem.
What is Budgeting? (The Tactical Operations)
Budgeting is tactical. It is the defensive playbook for your monthly cash flow. It answers the question: “How much can we spend on groceries, utilities, and entertainment right now without going into debt?”
A budget focuses on the short term—usually monthly or bi-weekly. It tracks cash entering your checking account and controls cash leaving it. Without a budget, you risk spending blindly, accumulating surprise credit card debt, and wondering why you never have cash at the end of the month.
What is Financial Planning? (The Strategic Vision)
Financial planning is strategic. It is the offensive playbook for your life. It answers the question: “Where are we taking our family over the next 5, 10, or 20 years, and how do our assets support those goals?”
A financial plan focuses on the long term. It incorporates major life projects, retirement timelines, insurance strategies, investment allocations, and risk management. Without a financial plan, a budget is just a list of restrictions. You might successfully save $500 a month in your checking account, but if you don't know why you are saving it or where it should be deployed, that money loses its power.
The Analogy of the Ship: Think of your family as a ship crossing the ocean. Budgeting is the crew managing the sails, trimming the canvas, and making sure water isn't coming through the hull today. Financial planning is the captain holding the compass, charting the coordinates, and ensuring the ship actually reaches the desired continent. You need both a competent crew and a clear map to survive the voyage.
2. Why Relying on Budgeting Alone Leaves Couples Frustrated
Most couples start their financial journey by building a budget. They divide their income into categories: Housing, Food, Transport, Savings. They try to restrict their spending to hit arbitrary targets.
Inevitably, friction arises. Why? Because budgets deal in limitations. When one spouse wants to buy a $120 pair of running shoes and the budget says "Discretionary allowance exhausted," it feels like a punishment. Over time, budgeting alone breeds resentment because it forces couples to constantly police each other's micro-decisions without connecting those sacrifices to a larger, inspiring vision.
When you introduce a Financial Plan, the psychological dynamic shifts completely. Cutting back on dining out stops feeling like deprivation and starts feeling like an intentional trade-off: "We are skipping Friday takeout for the next three months so we can fund our family sabbatical next summer." Vision defeats restriction every single time.
3. The Numbers Game: A Real-World Dollar Breakdown
Let’s look at how budgeting and financial planning integrate seamlessly for a realistic middle-class married couple: Thomas and Clara.
Thomas and Clara have a combined net monthly income of $7,500 ($90,000 per year after taxes). They have two children, own one car, rent a townhouse, and want to balance living comfortably today while funding three major future priorities: a family emergency fund, their children’s education accounts, and retirement.
Thomas and Clara use a dual framework:
The Strategic Financial Plan (The Blueprint): Allocates 20% of their net income ($1,500/month) toward long-term wealth, retirement compounding, and life project milestones.
The Tactical Budget (The Operating System): Distributes the remaining 80% ($6,000/month) across daily survival (Needs) and lifestyle enjoyment (Wants).
| Category | Type | Monthly Dollar Amount | Specific Allocation Details |
|---|---|---|---|
| Needs (Survival) | Budget (Tactical) | $3,800 | Rent ($1,700), Groceries ($750), Utilities & Internet ($350), Car Loan, Gas & Insurance ($650), Health Insurance ($350). |
| Wants (Lifestyle) | Budget (Tactical) | $2,200 | Family Dining/Coffee ($450), Kids Activities/Hobbies ($350), Personal Allowance (Thomas: $300, Clara: $300), Family Vacation Fund ($500), Subscriptions/Misc ($300). |
| Wealth & Milestones | Financial Plan (Strategic) | $1,500 | Emergency Fund Buffer ($500), Retirement Accounts / 401(k) ($600), Kids' Future Education Fund ($400). |
Notice how clean this separation is. Thomas and Clara never argue about Thomas’s $300 personal allowance or Clara’s hobby expenses because those are locked into the tactical budget. Meanwhile, their strategic financial plan quietly accumulates $1,500 every single month toward their long-term security without requiring daily thought.
4. Life Projects and Milestone Planning: Bringing the Plan to Life
A financial plan is only as good as its milestones. Saying "we are saving for the future" is too vague to motivate anyone. Families need structured life projects broken down into clear, chronological milestones with specific financial targets.
Let’s look at a concrete multi-year project for Thomas and Clara: Building Financial Independence & Reaching Milestone Security over a 36-month window.
Milestone 1: The Emergency Fortress & Debt Clean-up (Months 1–12)
Strategic Objective: Establish a bulletproof safety net before accelerating investments.
Financial Target: Accumulate a full 6-month emergency reserve ($22,800) and eliminate $6,000 in consumer credit card balances.
Action Plan: Direct the strategic $500/month emergency allocation into a High-Yield Savings Account (HYSA) while redirecting $300/month from optimized grocery shopping into debt payoff.
Result at Month 12: Zero toxic debt, freeing up extra cash flow, and a fully funded emergency reserve.
Milestone 2: The Wealth Acceleration & Investment Phase (Months 13–24)
Strategic Objective: Put accumulated capital to work through compounding interest and tax-advantaged accounts.
Financial Target: Maxify retirement contributions and build the first $10,000 baseline in the kids' college fund.
Action Plan: Increase strategic contributions to $1,800/month (utilizing a $300/month salary raise secured by Thomas). Maintain the tactical operating budget without lifestyle inflation.
Result at Month 24: Investment portfolio crosses $35,000 total valuation, generating passive interest growth.
Milestone 3: The Major Life Project Execution (Months 25–36)
Strategic Objective: Execute a major family life project (purchasing a larger suburban home or launching a family business venture).
Financial Target: Secure a $45,000 project capital pool while maintaining all ongoing retirement and emergency buffers.
Action Plan: Direct 100% of annual tax refunds ($4,000 average) and performance bonuses directly into the project pool while maintaining the $1,800/month baseline savings rate.
Result at Month 36: Project target reached safely on schedule without ever disrupting the family's daily lifestyle or tapping into retirement funds.
By using this milestone structure, Thomas and Clara see exact checkpoints. They know precisely where they are on their financial roadmap at any given moment.
5. Money & Relationships: Keeping Harmony Between Plan and Budget
Even with a brilliant financial plan and an efficient monthly budget, money can occasionally cause tension in a marriage if communication breaks down. Here are three golden rules to keep your partnership thriving as you execute your plan.
1. Separate Strategy Meetings from Tactical Reviews
Do not mix your daily budgeting with your long-term financial planning. If you are arguing about whether a $40 grocery bill was necessary while trying to discuss your 10-year retirement strategy, you will quickly become overwhelmed.
The Tactical Check-In (Bi-Weekly, 15 minutes): Review checking account balances, upcoming bills, and immediate category adjustments. Keep it practical and administrative.
The Strategic Money Date (Semi-Annually, 1 to 2 hours): Review your financial roadmap, celebrate milestone achievements, and adjust your life project goals over coffee or dinner out.
2. Guard Individual Autonomy Within Shared Goals
A common mistake in couple finances is trying to control every single dollar together. Total financial enmeshment often breeds resentment. When both partners have guaranteed personal allowances built into the tactical budget, they retain a sense of freedom. You can plan your financial future together as a team while still maintaining personal independence in your day-to-day choices.
3. Embrace the "Life Happens" Buffer
No financial plan or budget survives contact with reality untouched. Kids get sick, appliances break down, and inflation fluctuates. If your plan breaks down the moment an unexpected $350 expense hits, your plan was too rigid. Build grace into your system with an operating buffer. When minor crises occur, they are absorbed by the buffer without inducing panic or blame between spouses.
Conclusion: The Power of Having Both
Budgeting and financial planning are two sides of the same coin. Budgeting gives you control over your present, ensuring you live within your means and avoid the trap of lifestyle debt. Financial planning gives you a compass for your future, ensuring your hard work translates into meaningful life projects, security, and generational freedom.
When married couples stop relying solely on restrictive monthly budgets and instead build a comprehensive financial roadmap anchored by clear milestones, money transforms from a source of daily stress into a powerful tool for building a shared life.
Turn this into your own plan
Set up your household in ten minutes and see your projects on a real timeline.
Start freeKeep reading
Joint vs. Separate Bank Accounts for Married Couples: Which Is Best?
Budget & SavingWedding Budget Calculator: How Much Will Your Wedding Cost?
Money & RelationshipsHow Much Can You Spend Without Asking Your Partner?
Budget & SavingHow Much Emergency Fund Should We Have Before Starting a Major Project?
Financial RoadmapsWhat Happens Financially If Our Situation Changes? A Practical Guide for Couples
Financial RoadmapsJoint, Separate, or Hybrid Bank Accounts: What Works Best for Couples?
MilestonesMilestone-Based Financial Planning for Couples: A Guide to Securing Your Future Together
Budget & SavingHow to Build a Couple Budget That Actually Works (Without the Fight)
Money & RelationshipsHow to Align Your Financial Goals Before Buying a Home Together
Financial PlanningWhy Most Couples Don't Need a Better Budget — They Need a Better Timeline
Life ProjectsHow to plan a home purchase without derailing your other goals
BudgetingBudget planning for couples: a simple method that actually lasts
BudgetingBudget planning for couples: a simple method that actually lasts